
IFR/IFD · EU Regulation 2019/2033
K-factors daily.
Without the complexity
Calculate K-factors and the base own funds requirement for EU investment firms under the Investment Firms Regulation and Directive (IFR/IFD). Run daily calculations and internal monitoring. Class 2 firms report quarterly and Class 3 firms generally report annually. Everix prepares all 44 active EBA template codes.
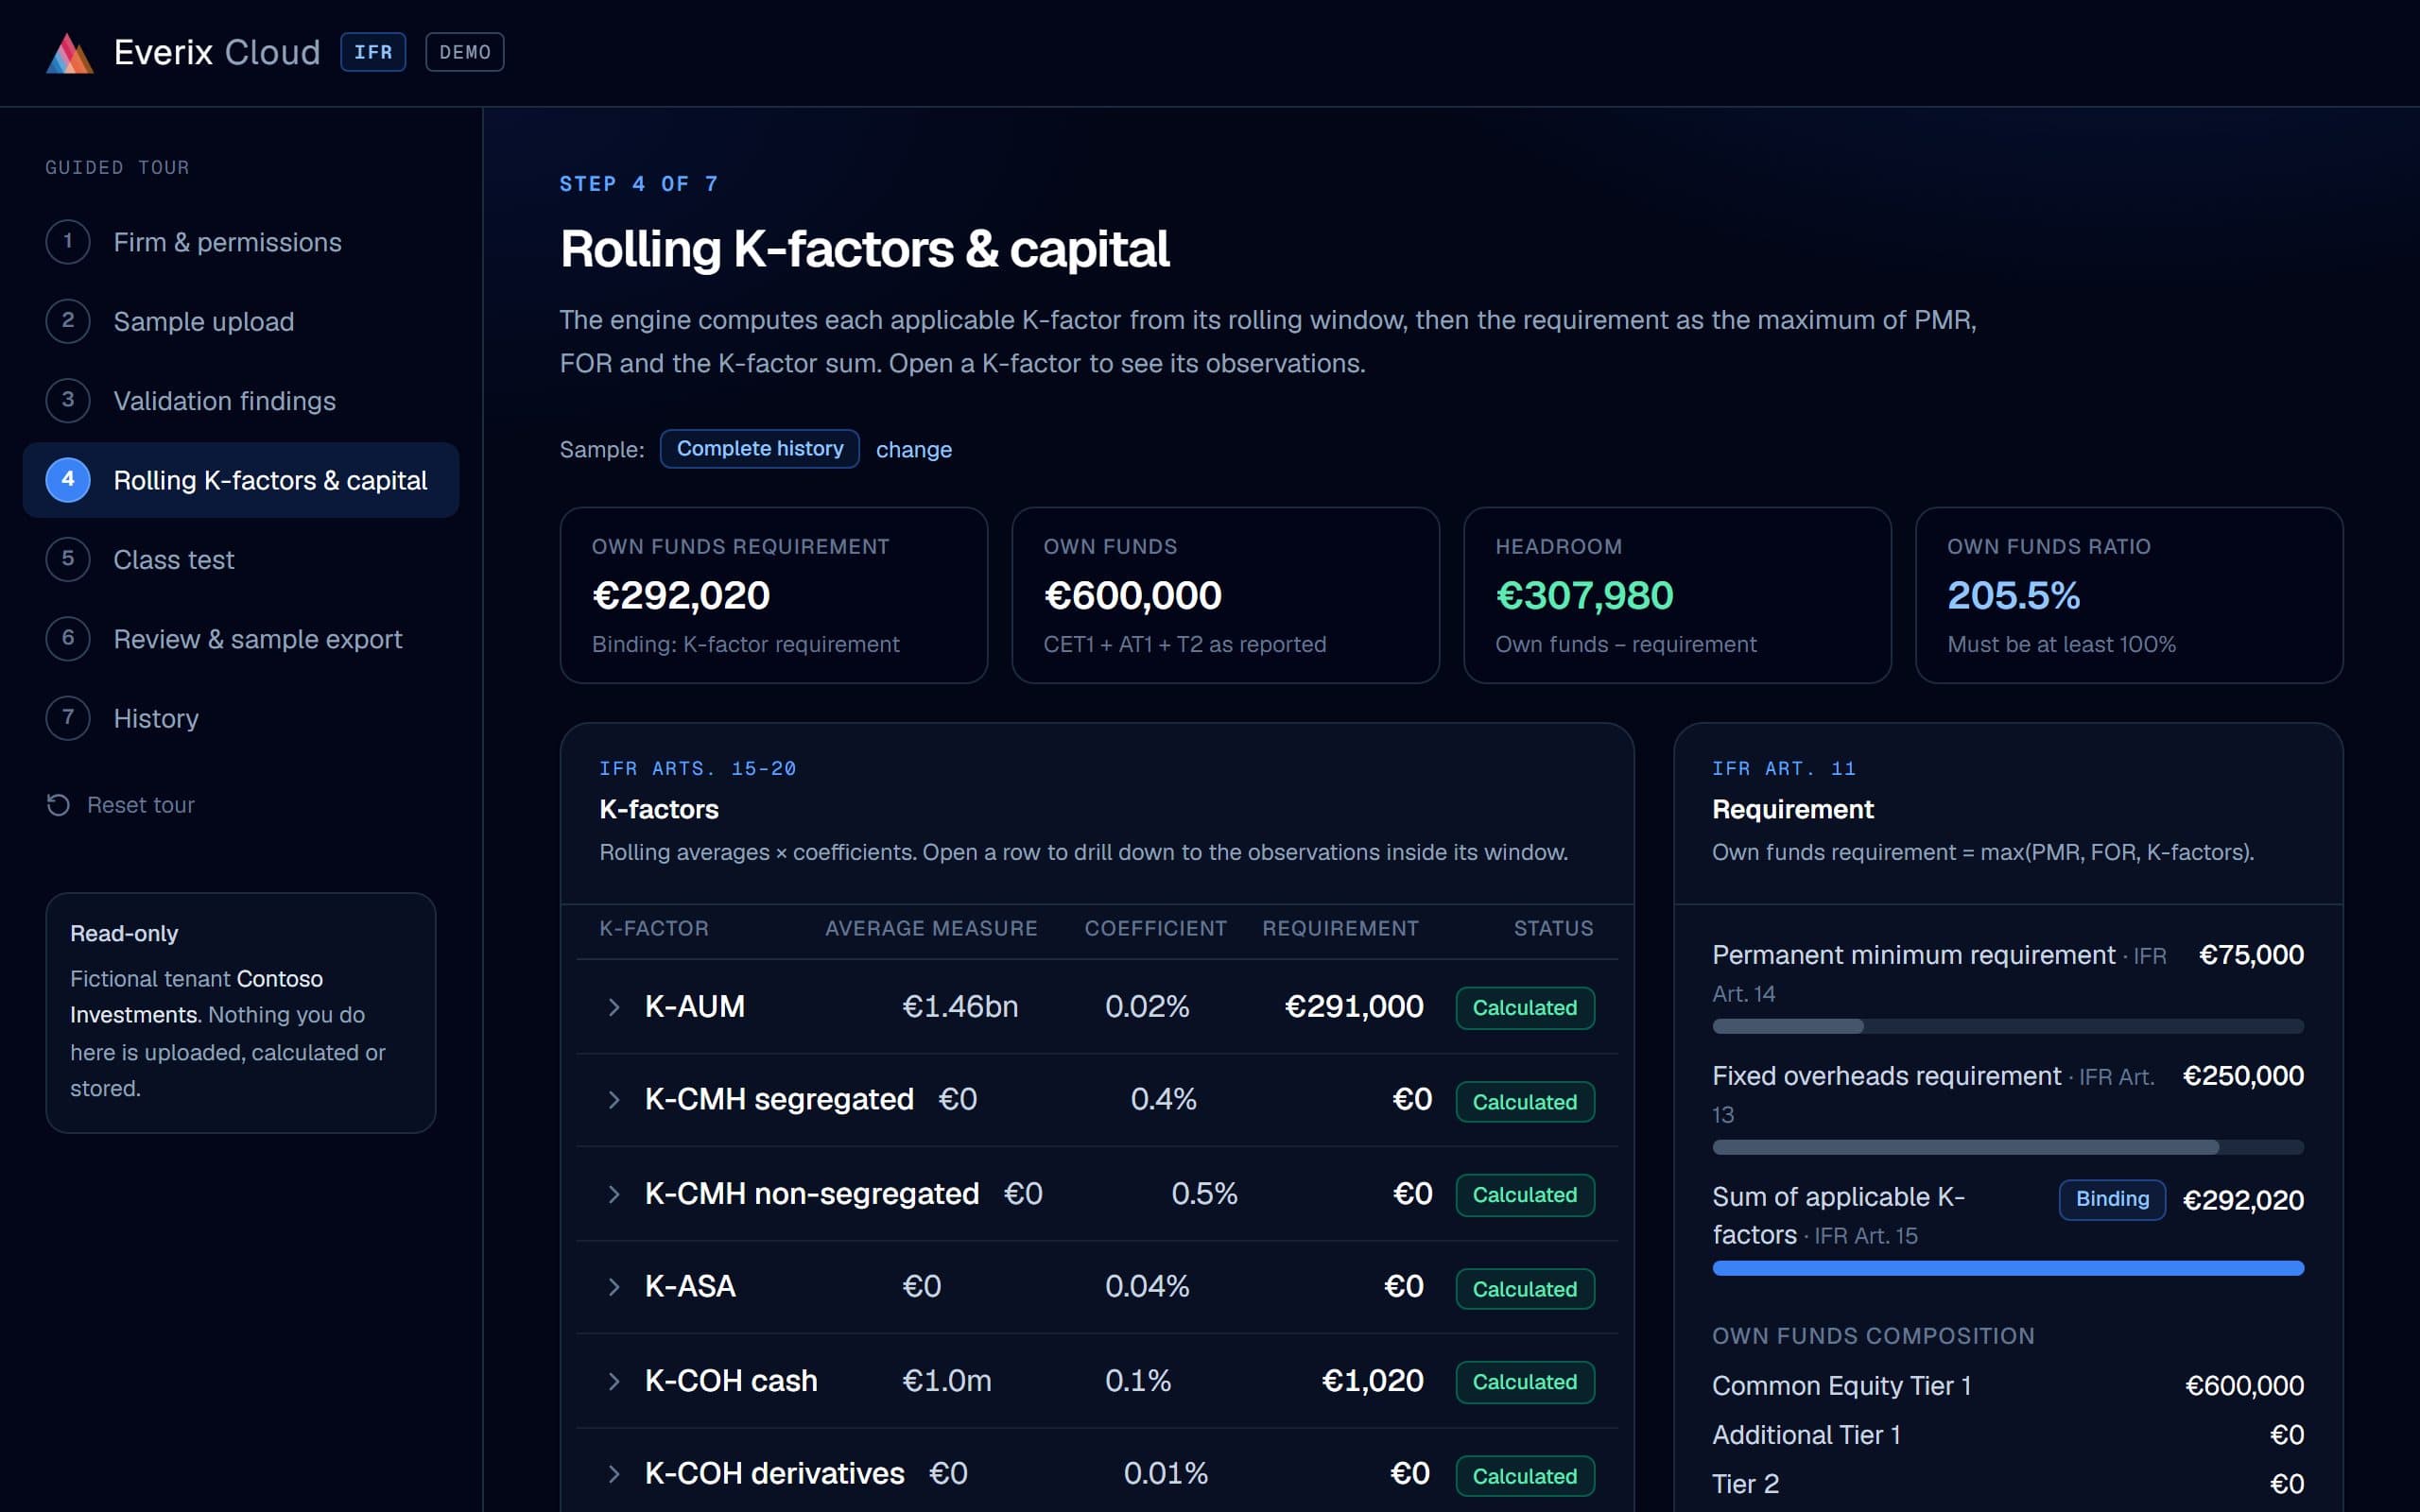
Product screens on this page show synthetic demo data; other figures are illustrative. No client data is shown.
Where you can run it
Compare deployment options| Capability | Everix Cloud IFR | Everix Cloud Risk | Everix Private Cloud | Everix On-site |
|---|---|---|---|---|
| IFR/IFD K-factors and own funds | AvailableClass 2, Class 3 and groups | Not offeredSee Everix Cloud IFR | AvailableClass 2, Class 3 and groups | AvailableClass 2, Class 3 and groups |
| EBA xBRL-CSV reporting (IFR) | AvailableSame pack as installed | Not offeredSee Everix Cloud IFR | Available | Available |
| ACPR (France) national checks | AvailableCalendar and national checks | Not offered | AvailableCalendar and national checks | AvailableCalendar and national checks |
| UK MIFIDPRU (FCA) | Not offeredEU IFR/IFD only | Not offered | Not offeredEU IFR/IFD only | Not offeredEU IFR/IFD only |
- Everix Cloud IFR
- AvailableClass 2, Class 3 and groups
- Everix Cloud Risk
- Not offeredSee Everix Cloud IFR
- Everix Private Cloud
- AvailableClass 2, Class 3 and groups
- Everix On-site
- AvailableClass 2, Class 3 and groups
- Everix Cloud IFR
- AvailableSame pack as installed
- Everix Cloud Risk
- Not offeredSee Everix Cloud IFR
- Everix Private Cloud
- Available
- Everix On-site
- Available
- Everix Cloud IFR
- AvailableCalendar and national checks
- Everix Cloud Risk
- Not offered
- Everix Private Cloud
- AvailableCalendar and national checks
- Everix On-site
- AvailableCalendar and national checks
- Everix Cloud IFR
- Not offeredEU IFR/IFD only
- Everix Cloud Risk
- Not offered
- Everix Private Cloud
- Not offeredEU IFR/IFD only
- Everix On-site
- Not offeredEU IFR/IFD only
Regulatory Coverage
All three factor families.
The engine calculates FX and commodity K-NPR. Debt, equity, securitisation and internal-model amounts, and K-CON, are figures your firm attests. K-CMG needs competent-authority permission.
Risk-to-Market (RtM) Factors
K-NPR uses the CRR market-risk approaches for trading-book positions and non-trading-book FX and commodity risk. K-CMG is an alternative for eligible cleared positions or qualifying cleared/margined portfolios, subject to competent-authority permission and IFR Article 23 conditions.
Synthetic illustration · K-NPR by asset class (EUR k)
Risk-to-Clients (RtC)
- K-COH: IR notional × maturity in years / 10 (Art. 20)
- AUM: monthly values; CMH/ASA/COH: daily values
- Rolling windows exclude the latest 3 months (Arts 17–20)
Risk-to-Firms (RtF)
- RC + PFE − recognised collateral per legal netting set
- IFR PFE; SA-CCR / simplified SA-CCR / OEM with Article 25(4) permission
- Netting with collateral & CSA
- Daily concentration monitoring
Dashboards & limits
Always in view
Roadmap preview: dedicated IFR dashboards for risk management and executives. Limit utilisation tracked continuously with breach alerts for trading and compliance.
Know the capital impact before you trade
Simulate any trade, book, or market scenario and see its effect on K-factors. Run from the Everix UI or via the Risk API from your front-office system.
Single Trade Impact
- K-NPR, K-TCD, K-CON delta
- Incremental capital cost
- Best counterparty routing
Book Simulation
- Simulate groups or full book
- New + modified + cancelled trades
- Aggregate K-factor impact
Market What-if
- Combine with market data bumps
- Rate, FX, spread shocks
- Regulatory stress scenarios
Front-office Integration
- Connect via the Everix Risk API
- Run what-if from your OMS/EMS
- Real-time capital pre-screening
VaR and IM
in the same picture
Run VaR, licensed ISDA SIMM™ initial margin and IFR K-factors alongside one another on a shared portfolio for internal risk management. VaR and bilateral SIMM are not direct IFR K-factor inputs. Recognised collateral affects exposure only under IFR eligibility and haircut rules.
Shared portfolio · separate methodologies
VaR
Internal market-risk measure; not a direct K-factor input
ISDA SIMM™
Bilateral initial margin; not a direct K-factor input
IFR/IFD
K-factors under IFR methods and permissions
Reports, BI and the public API. Everix prepares and checks the pack; your team approves it and files it.
Related modules
XVA
CVA, DVA, FVA with automatic explain and what-if. XVA and native IFR K-TCD use distinct exposure methods on the same trade data.
ExploreISDA SIMM™
Licensed ISDA SIMM™ initial margin calculator — runs alongside IFR on the same portfolio.
ExploreSA-CCR
SA-CCR exposure may be used for K-TCD with Article 25(4) permission; apply the IFR risk factor and CVA factor.
ExploreAll Everix modules.
One portfolio view.
IFR/IFD K-factors sit alongside market risk, counterparty exposure, XVA, and Initial Margin — all computed on the same portfolio. Collateral posted under each CSA is accounted for, so capital and exposure figures reflect your actual net position.
See IFR/IFD in your portfolio
We'll walk you through the platform with a real use case, explain the methodological choices, and tell you plainly if Everix is the right fit.
Illustrative module dataset, 15 January 2026; amounts in EUR. CVA is shown as a positive cost magnitude (314,397 prior day + 111,960 movement = 426,357). DVA is shown as a negative cost. Exposure, own funds requirements and posted initial margin are separate metrics. K-TCD uses native IFR EV = 2,500,000, α = 1.2, RF = 1.6% and CVA factor = 1.5: K-TCD = 72,000.