
XVA module
Monte Carlo XVA,
explained to the trade
Monte Carlo CVA, DVA, FVA and LVA, with collateral simulated per CSA and each charge allocated to the trade and the leg. In production since 2018.
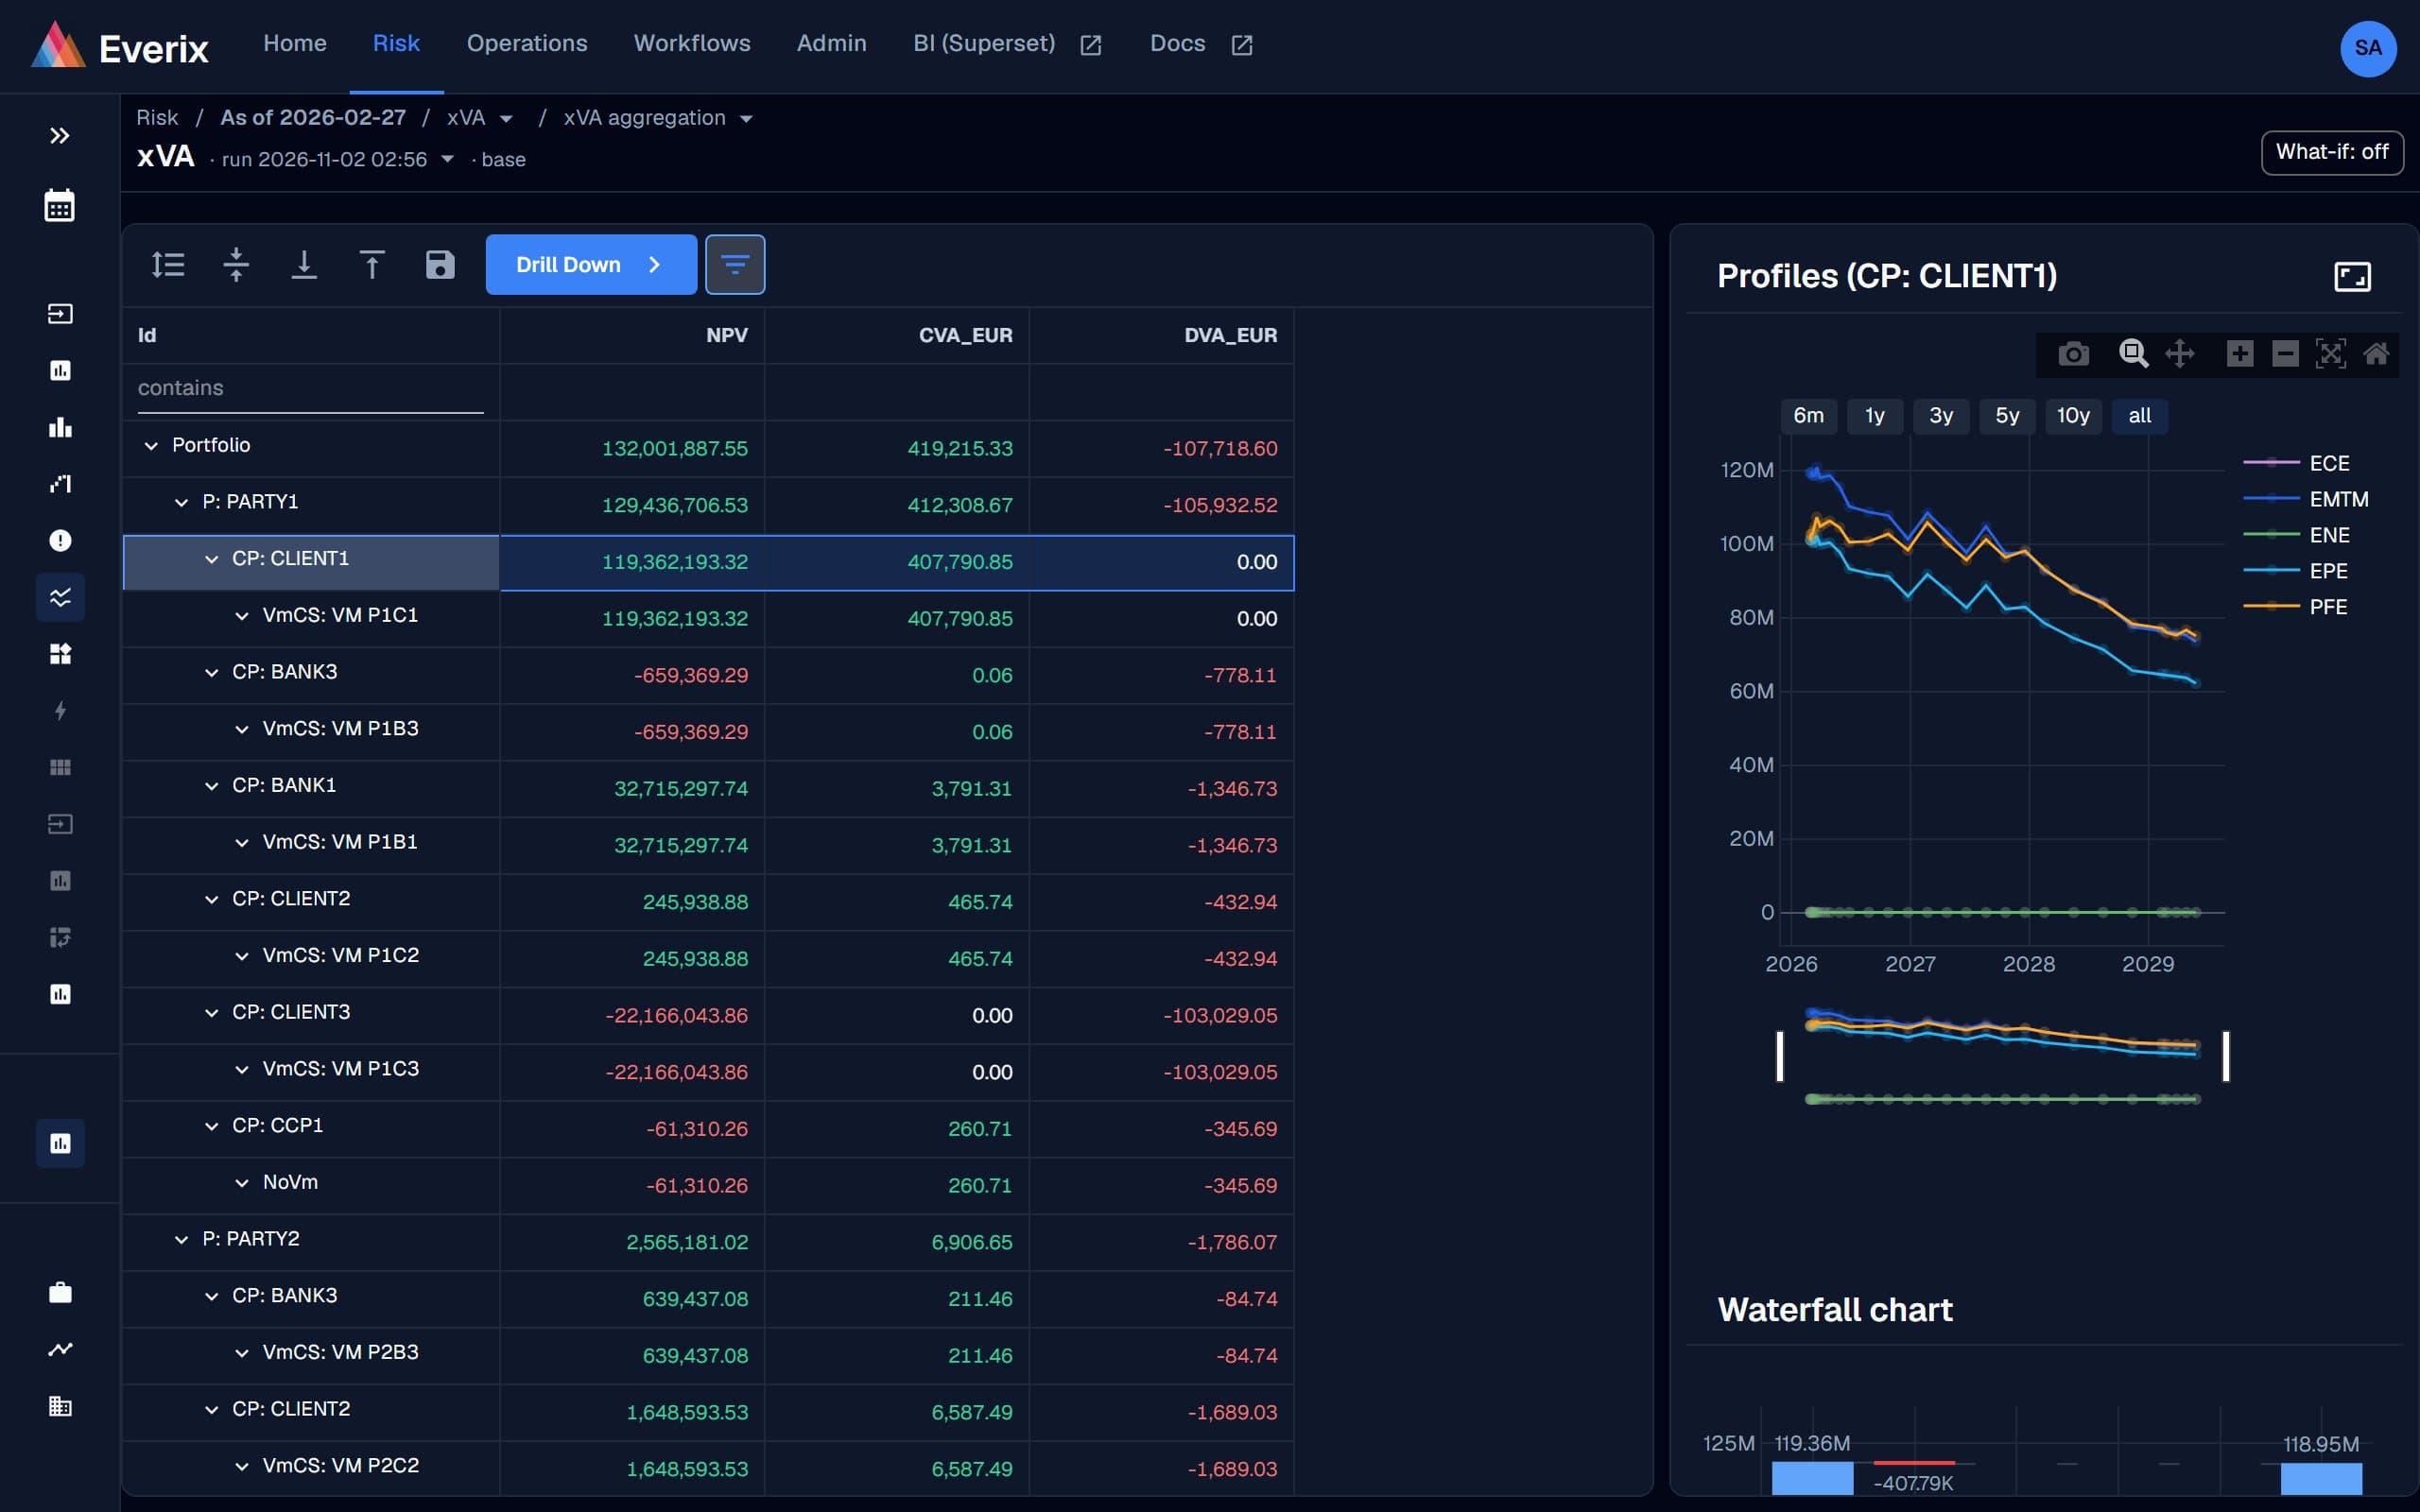
Product screens on this page show synthetic demo data; other figures are illustrative. No client data is shown.
Where you can run it
Compare deployment options| Capability | Everix Cloud IFR | Everix Cloud Risk | Everix Private Cloud | Everix On-site |
|---|---|---|---|---|
| XVA: CVA, DVA, FVA, LVA | Not offeredIFR service | On requestScoped with you | Available | AvailableIn production since 2018 |
| MVA and KVA | Not offered | Not offered | Early accessBoth in early access, built with design partners | Early accessBoth in early access, built with design partners |
| Sensitivities and what-if | Not offered | On requestScoped with you | Available | Available |
- Everix Cloud IFR
- Not offeredIFR service
- Everix Cloud Risk
- On requestScoped with you
- Everix Private Cloud
- Available
- Everix On-site
- AvailableIn production since 2018
- Everix Cloud IFR
- Not offered
- Everix Cloud Risk
- Not offered
- Everix Private Cloud
- Early accessBoth in early access, built with design partners
- Everix On-site
- Early accessBoth in early access, built with design partners
- Everix Cloud IFR
- Not offered
- Everix Cloud Risk
- On requestScoped with you
- Everix Private Cloud
- Available
- Everix On-site
- Available
How the exposure is computed
Calibration, diffusion, pricing on every path and aggregation run as one scheduled workflow. Every metric opens down to the deal and the leg that produced it.
Monte Carlo simulation
Correlated diffusion of interest rates, FX, credit spreads and equity, priced with Everix models or your own pricing library. Collateral is discounted per CSA, and the same exposures feed SA-CCR and RWA.
Expected Positive Exposure — CP: BANK13
Collateral, simulated per CSA
Variation and initial margin are simulated on every path, so thresholds, minimum transfer amounts and the margin period of risk show up in the exposure and in the funding cost.
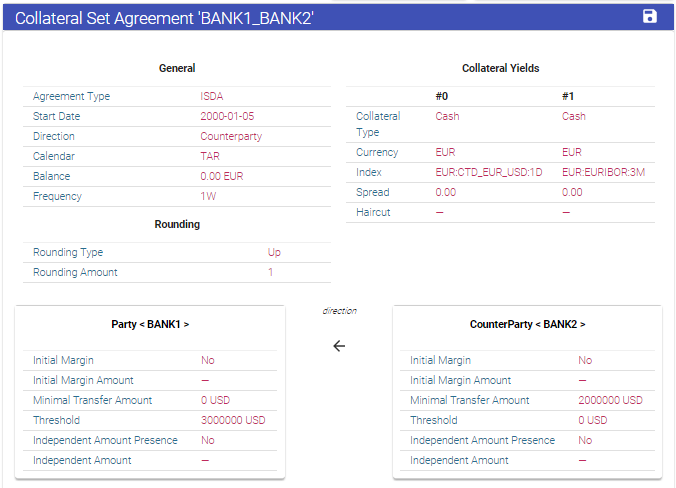
- MTA, MPOR, rounding
- VM & IM simulation
- Multiple CSA discounts
- Cheapest-to-deliver
- Collateral asymmetry
- Break clauses
Around XVA
XVA sensitivities and hedging
Compute XVA delta, gamma, and vega across all risk factors. Use to construct hedging portfolios that offset your XVA exposure.
- IR, FX, CO & credit spread sensitivities
- Integrate with your front-office hedging flow
Allocation to each trade
Each deal's marginal contribution to portfolio CVA, DVA, and FVA is computed and visible at deal and leg level — enabling accurate front-office charge attribution and pricing of new trades.
- Drill down to deal and leg level
- Marginal XVA for pre-trade pricing
- Allocation across netting sets
Why CVA moved overnight, factor by factor
Each daily run splits the change in CVA into new and matured trades, market moves, the passage of time, collateral terms and configuration, and the factors add up to the total.
Illustrative module dataset, 14 → 15 January 2026, EUR. The factors (+215,380 − 89,140 − 31,050 + 12,670 + 4,100) add up to the 111,960 CVA movement: 314,397 the prior day, 426,357 on 15 January.
Pre-trade XVA what-if and marginal impact
Change trades, market data or collateral terms and rerun the XVA on that scenario, from the Everix UI or from your front-office system through the REST API.
Trade what-if
- Novation impact
- Partial unwind
- New trade incremental
- Full portfolio unwind
Market data
- Scalar bumps
- Curve shifts and bumps
- Volatility surface/cube shifts
- Absolute and relative
CSA changes
- Threshold adjustment
- MTA change
- Discount curve switch
- Collateral currency
Custom scenarios
- Combine any changes
- Regulatory stress sets
- Historical scenarios
- Save and replay
One pipeline, on your servers or in your cloud.
Everix On-site installs on Windows Server in your data centre; Everix Private Cloud runs the same release on your Kubernetes or cloud account. A scheduled workflow loads the data, prices on every path and aggregates, and the same pipeline runs on a single server for smaller books.
XVA next to margin and capital
XVA, ISDA SIMM initial margin, SA-CCR exposure and liquidity costs come from the same trades and the same run, so they can be read side by side. Most metrics also have marginal and forward versions, and every level of the hierarchy exports to CSV.
Illustrative module dataset, 15 January 2026, EUR. CVA is a positive cost and DVA a negative one. Exposure, own funds and posted initial margin are separate metrics.
Related modules
SA-CCR
Standardised Approach for Counterparty Credit Risk — marginal, forward, pre-trade impact.
ExploreISDA SIMM™
Licensed ISDA SIMM™ initial margin, validated against ISDA's unit tests, with what-if analysis.
ExploreIFR / IFD
EU capital requirements for investment firms — K-factors, own funds, and regulatory reporting.
ExploreSee XVA in your portfolio
Bring a netting set to review exposure, collateral and XVA drivers. No paid proof of concept.