
SA-CCR · BIS CRE52 · EU CRR3
SA-CCR from trade
to exposure at default.
Calculate derivatives exposure at default under the standardised approach for counterparty credit risk (SA-CCR): netting, recognised collateral and supervisory add-ons. Apply the selected credit-risk treatment to derive RWA and capital. Pre-trade analysis runs in the UI or through the public API.
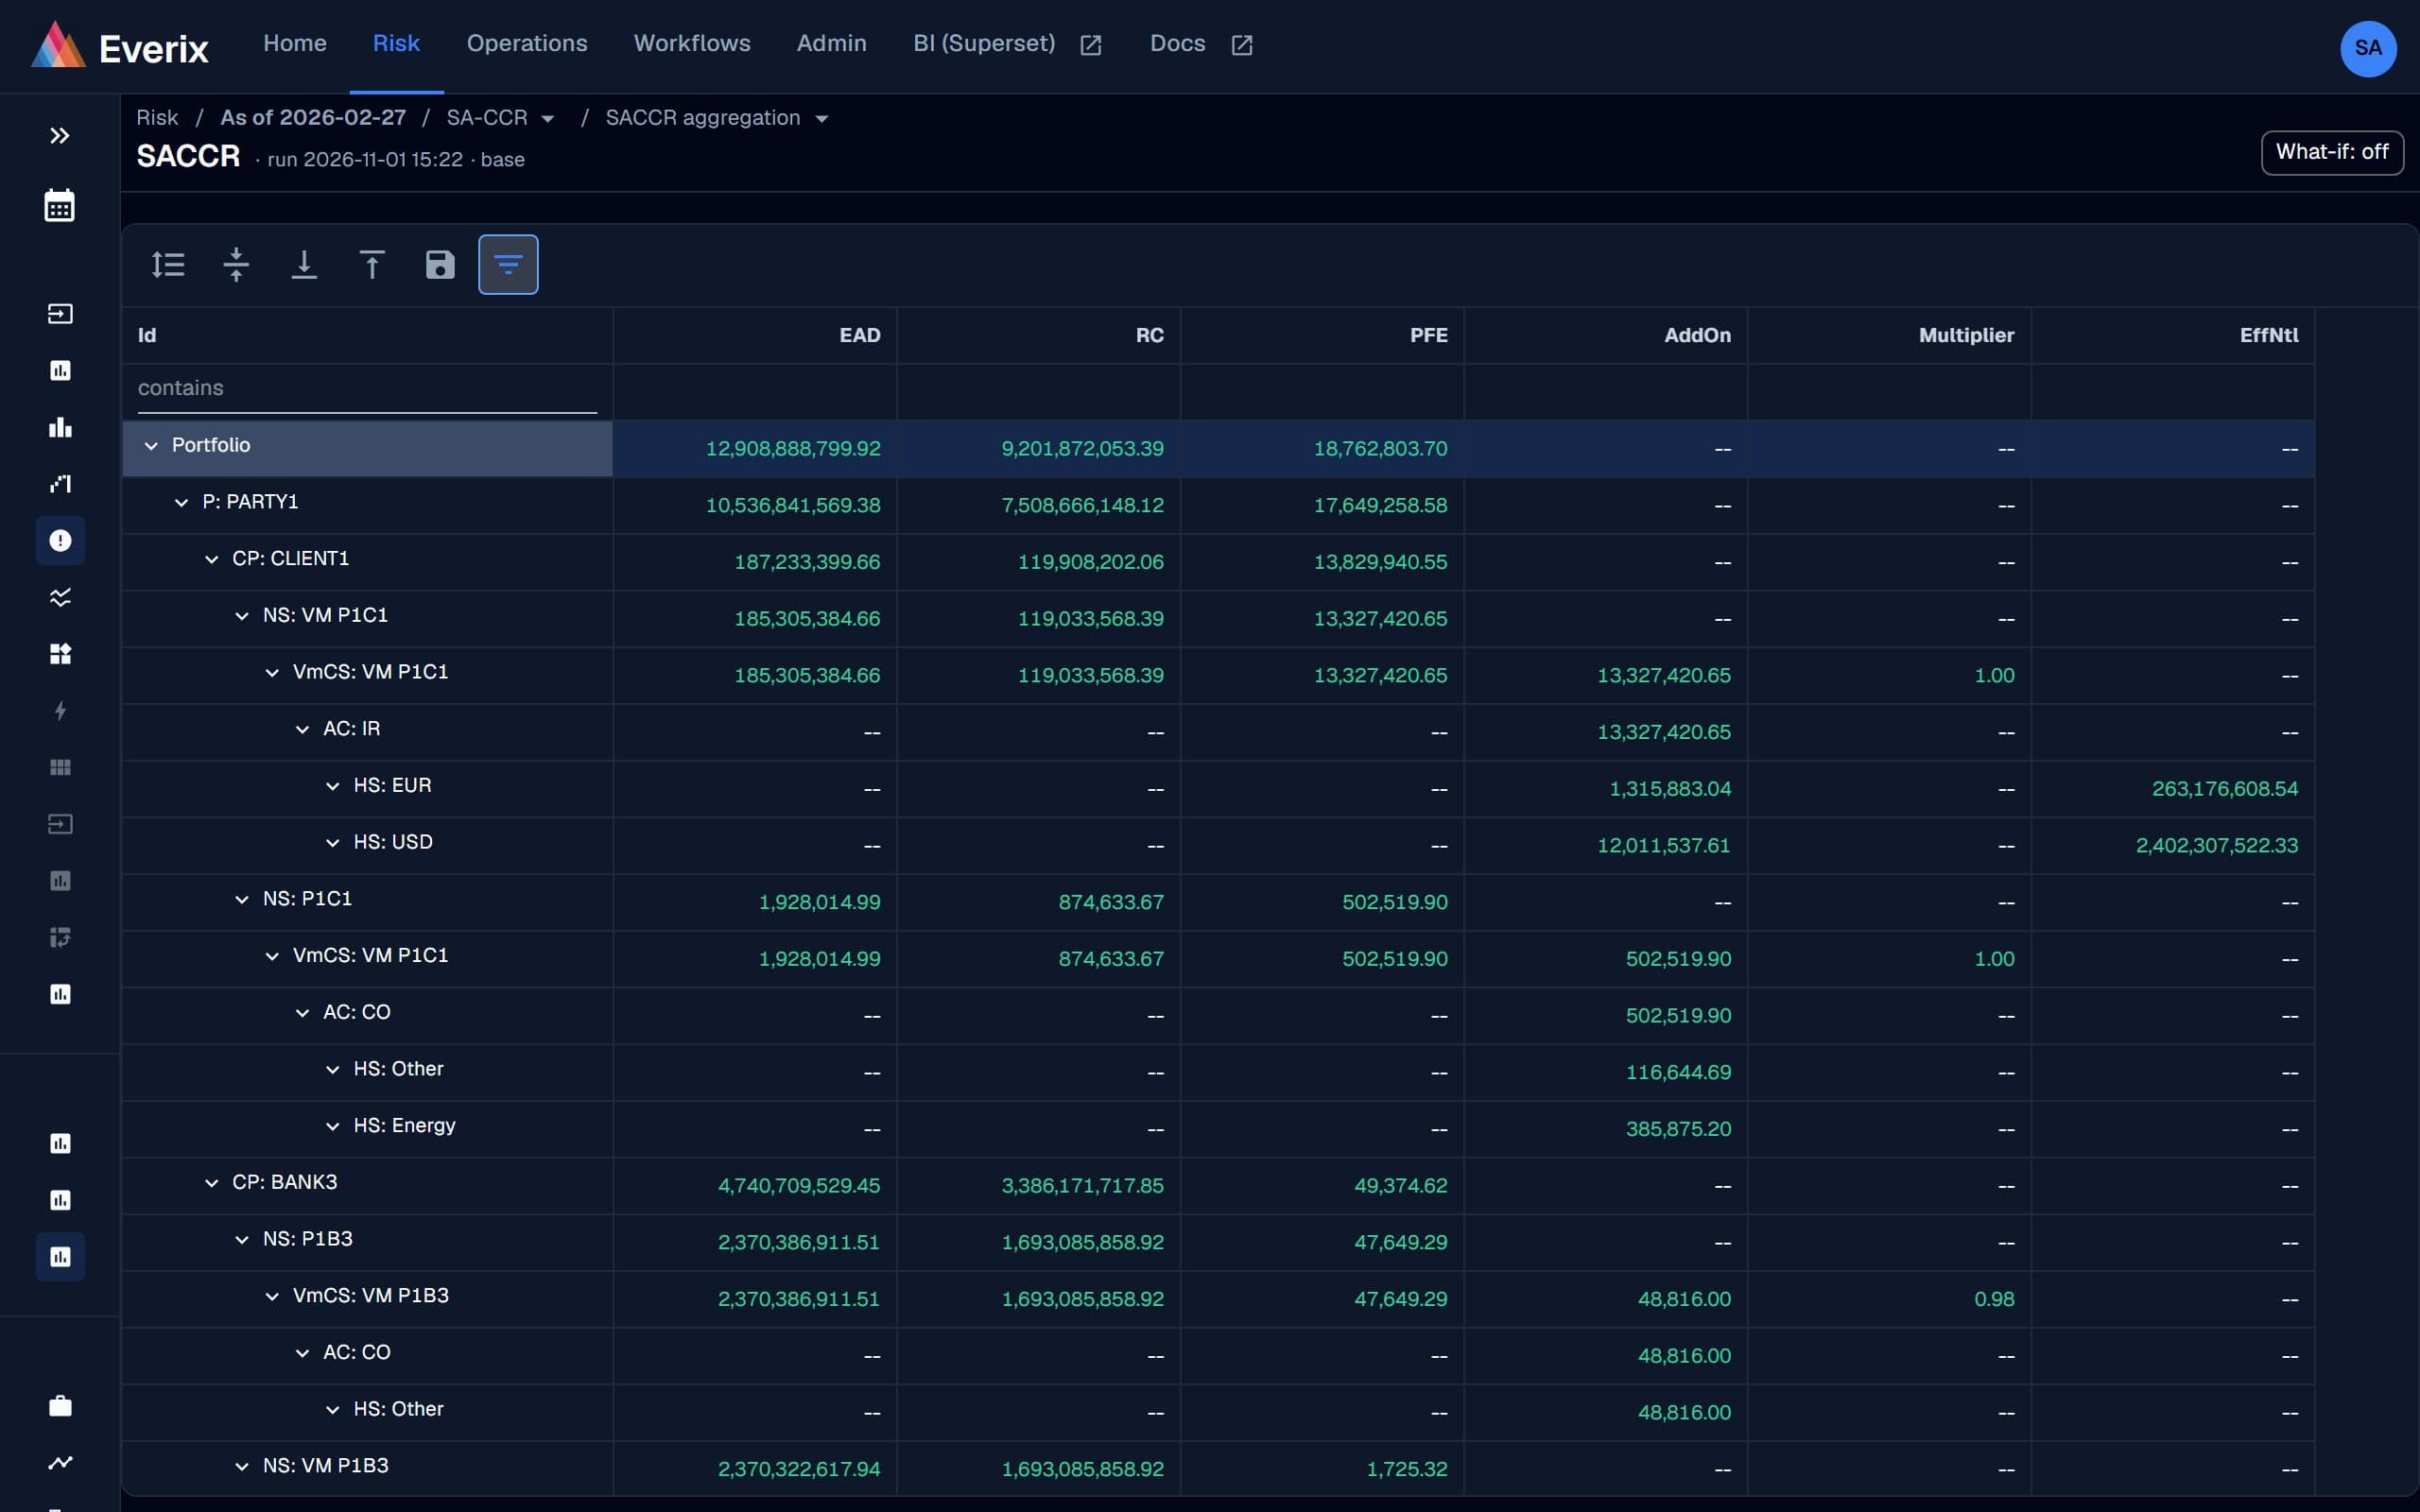
Product screens on this page show synthetic demo data; other figures are illustrative. No client data is shown.
Where you can run it
Compare deployment options| Capability | Everix Cloud IFR | Everix Cloud Risk | Everix Private Cloud | Everix On-site |
|---|---|---|---|---|
| SA-CCR | Not offeredIFR service | On requestScoped with you | AvailableValidated against the BCBS examples | AvailableValidated against the BCBS examples |
| Sensitivities and what-if | Not offered | On requestScoped with you | Available | Available |
- Everix Cloud IFR
- Not offeredIFR service
- Everix Cloud Risk
- On requestScoped with you
- Everix Private Cloud
- AvailableValidated against the BCBS examples
- Everix On-site
- AvailableValidated against the BCBS examples
- Everix Cloud IFR
- Not offered
- Everix Cloud Risk
- On requestScoped with you
- Everix Private Cloud
- Available
- Everix On-site
- Available
SA-CCR calculations with inspectable intermediate results
Validated against the BCBS 279 worked examples with published rounding, using CRR Articles 274–280f and adopted Delegated Regulation (EU) 2021/931. Example validation does not establish every portfolio case. Intermediate metrics are available for review.
Pay-off Decomposition & Auditability
Complex and exotic payoffs — barrier options, spread products, multi-legged structures — are decomposed on the fly into European options using supervisory volatilities. Every intermediate metric is visible down to the optlet level, enabling audit trails.
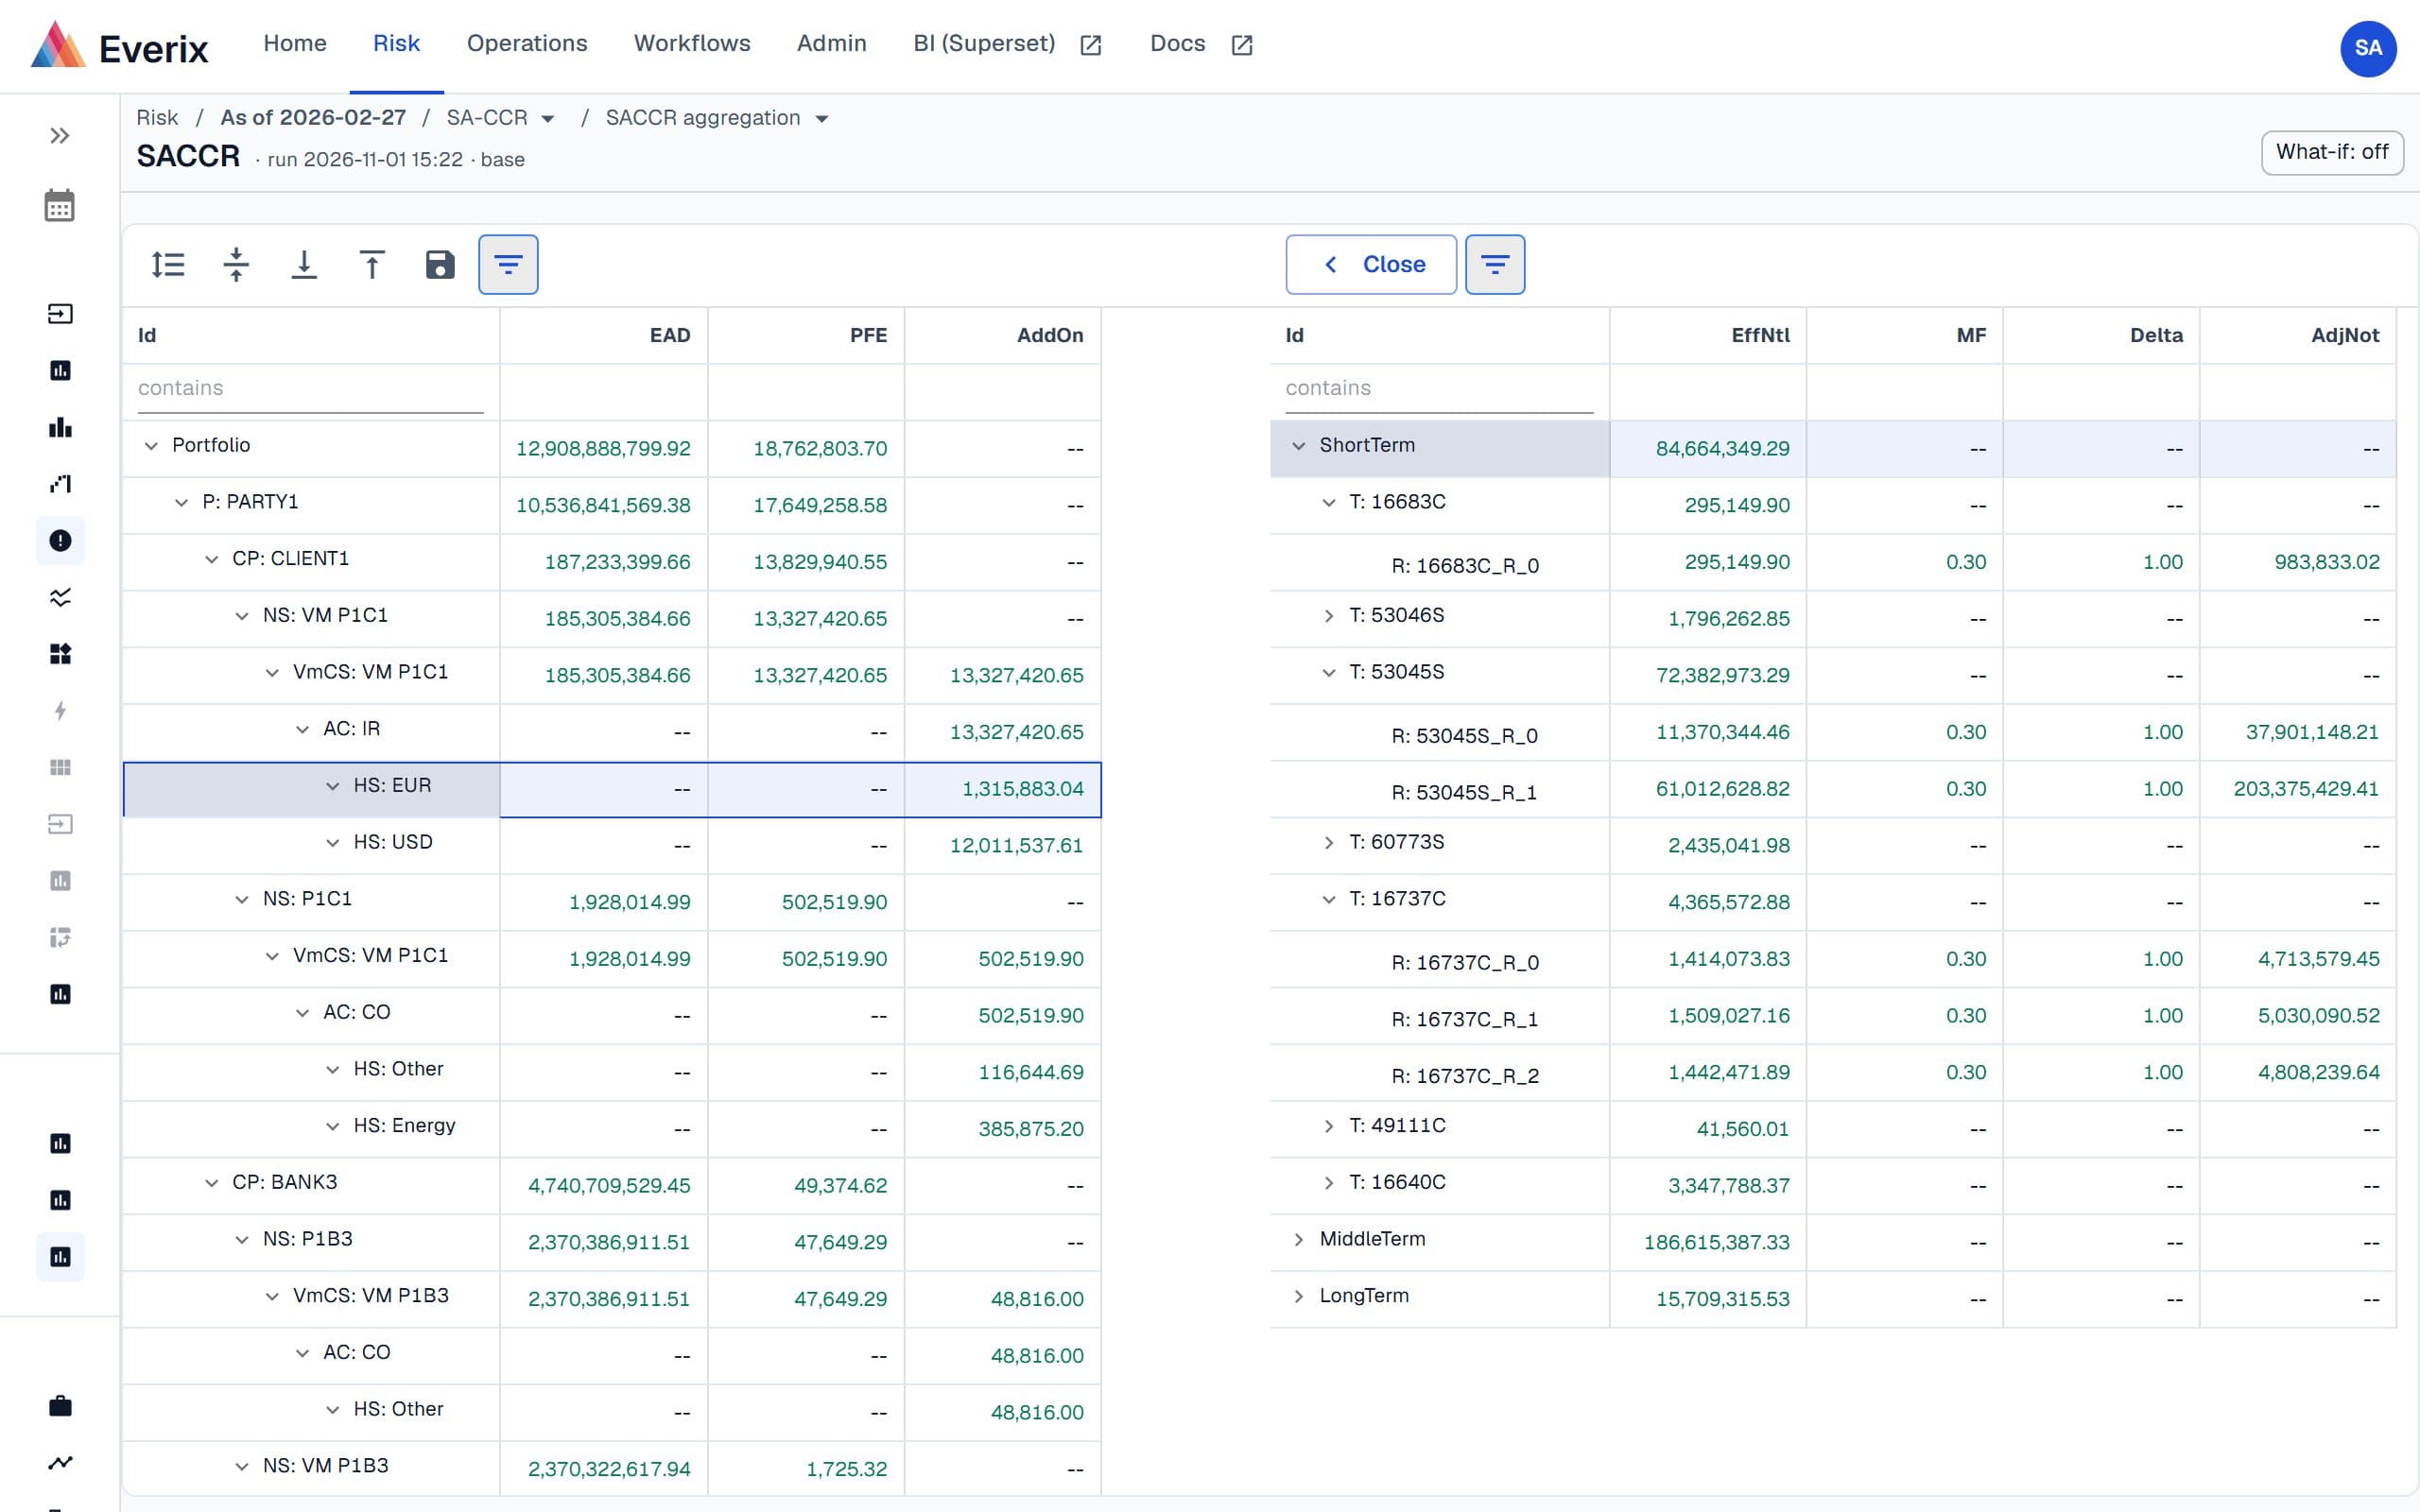
Replacement Cost
- Input or computed by Everix
- Netting & collateral set dependencies
- Comprehensive CSA representation
Dynamic Asset Class Allocation
Hybrid products are classified dynamically using FRTB-like sensitivities and risk weights, under the mapping methodology in Delegated Regulation (EU) 2021/931. Example: a IR/FX spread barrier is classified as FX, IR, or both depending on moneyness.
- FRTB-like sensitivities for hybrid products
- EBA asset class allocation rules
- Re-classification on market moves
Tailored Integration
Three ways to connect. One outcome.
Use Everix as a complete SA-CCR platform or as a modular engine extending your existing risk ecosystem. Choose the integration depth that fits your architecture.
Full Compute
Everix handles everything
Provide raw deals and market data. Everix runs the full pipeline: ETL, asset class classification, delta computation, supervisory PFE add-on calculation, and RC calculation.
- Raw trades + market data as input
- Everix classifies and prices
- Audit trail to optlet level
- Output: RWA, RC, PFE, EAD, AddOn
Your Sensitivities
Bring your deltas
Your system provides pre-computed sensitivities. Everix applies FRTB-like classification rules to assign asset classes and computes SA-CCR exposure.
- Provide FRTB-like sensitivities
- Everix classifies asset classes
- Handles hybrid/cross-asset products
- Reuse existing front-office analytics
Full Data
Maximum control
Provide both classification and sensitivities from your own systems. Everix applies the regulatory formula, aggregates, and outputs RC, PFE and EAD. Risk weighting and own funds calculations are separate steps.
- Bring your own classification
- Provide sensitivities directly
- Everix aggregates and computes
- Minimal footprint, maximum flexibility
Advanced Features
What-If Analysis
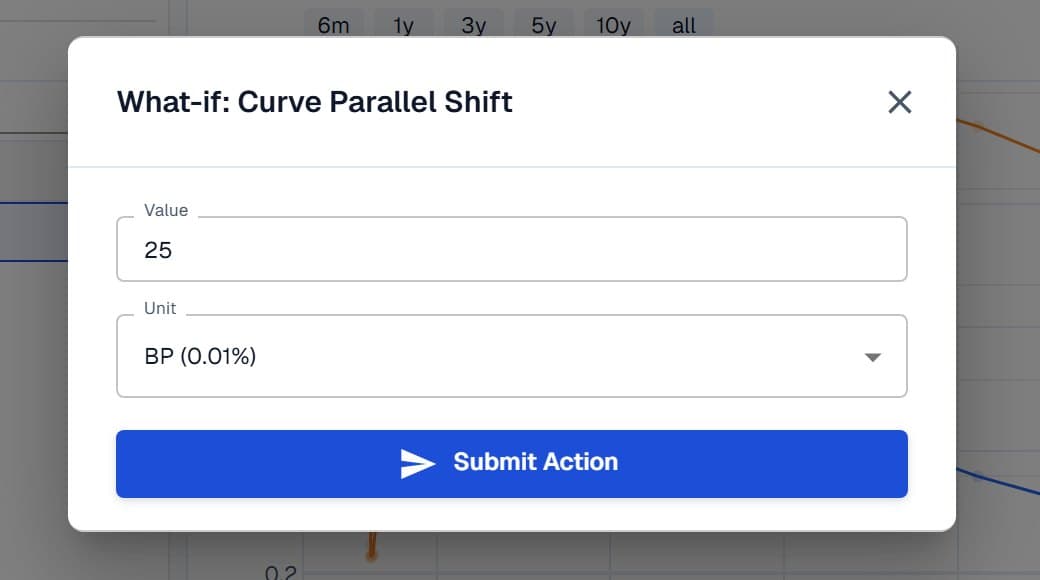
- Pre-trade incremental impact
- Market data bumps (curve shifts, surface)
- Trade-level add/remove/modify
- Run from the UI or the public API
Marginal SA-CCR
Each trade's marginal contribution to portfolio PFE and Replacement Cost — computed and visible at deal and leg level. Use for charge attribution, limit management, and netting set optimisation.
- PFE reallocation per trade
- RC reallocation per trade
- Drill down to deal & leg level
- Netting set contribution view
SA-CCR Forward · Early access
Project your SA-CCR capital cost over the lifetime of the portfolio. Forward RC and PFE are calculated using market data diffusion — giving you a full cost-of-capital curve over time.
- Forward RC based on diffusion
- Forward PFE over trade lifecycle
- Lifetime capital cost forecast
- Integrate into funding cost analysis
All Everix modules.
One portfolio view.
SA-CCR exposure sits alongside XVA, Initial Margin, market risk, and regulatory capital — all computed on the same portfolio. Collateral posted under each CSA is accounted for, so EAD and RWA figures reflect your actual net position.
Related modules
XVA
CVA, DVA, FVA and LVA from Monte Carlo exposure, with attribution and what-if; MVA and KVA in early access.
ExploreISDA SIMM™
Licensed ISDA SIMM™ initial margin, validated against ISDA's unit tests, with what-if analysis.
ExploreIFR / IFD
EU capital requirements for investment firms — K-factors, own funds, and regulatory reporting.
ExploreSee SA-CCR on your portfolio.
We'll run a demo on a real use case, show you the auditability and pre-trade features, and tell you plainly which integration option fits your stack.
Illustrative module dataset, 15 January 2026; amounts in EUR. CVA is shown as a positive cost magnitude (314,397 prior day + 111,960 movement = 426,357). DVA is shown as a negative cost. Exposure, own funds requirements and posted initial margin are separate metrics. SA-CCR illustration: unmargined sets, multiplier 1; RC totals 1,000,000 and unrounded PFE totals 1,029,642.857, giving EAD 2,841,500 at α = 1.4. IR SF = 0.5%, FX SF = 4%; values displayed rounded. K-TCD uses native IFR EV = 2,500,000, α = 1.2, RF = 1.6% and CVA factor = 1.5: K-TCD = 72,000.